Institute
louis
Bachelor
louis
Bachelor


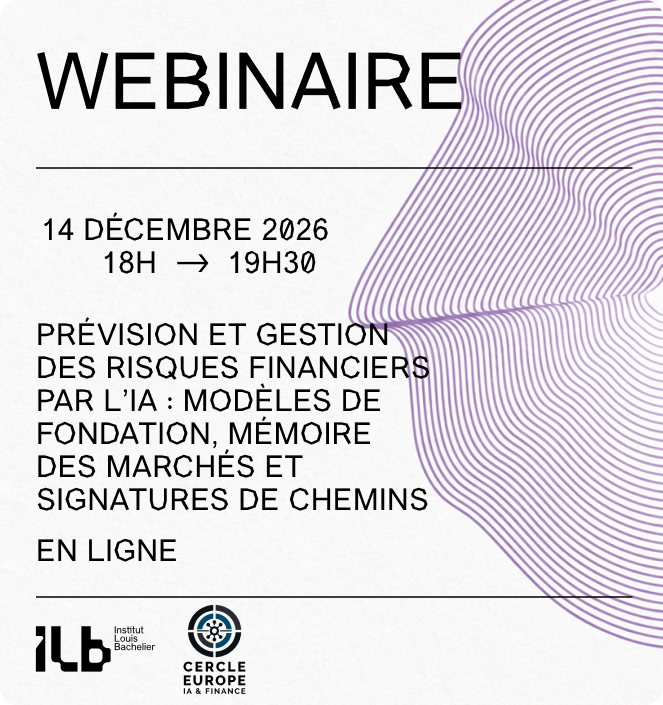


On December 14, 2026, from 6:00 PM to 7:30 PM, Christophe Hurlin and Eduardo Abi Jaber will present two approaches for advancing financial risk forecasting and management through artificial intelligence.
Given the increasing complexity of markets and the growing demands of risk management, how can new AI approaches enhance traditional modeling methods? This meeting will offer insights at the intersection of artificial intelligence, econometrics, and financial mathematics, through two complementary studies.
Christophe Hurlin will explore the contribution of foundation models applied to tabular data for credit risk estimation. His presentation will examine the prospects these models offer for financial data analysis and risk assessment.
Eduardo Abi Jaber will focus on market memory and how accounting for it can improve volatility forecastingand thehedging strategy optimization.
A roundtable discussion bringing together researchers and financial sector professionals will follow the presentations. It will compare scientific advancements with operational realities, focusing on several key issues: performance gains, model robustness, explainability, regulatory constraints, and adoption conditions within financial institutions.
The goal: to better understand the possibilities offered by these approaches and the conditions necessary for their use in risk management.
Practical information
📅 Monday, December 14, 2026
🕕 From 6:00 PM to 7:30 PM, online
👉 Register for the webinar : https://events.teams.microsoft.com/event/0edc5d98-782c-4c41-9f2c-6a6f5e15720a@15c185cf-bb12-45d5-bcd3-6ba3057b70f6?source=copyLinkLegacyShareEventDialog