Institute
louis
Bachelor
louis
Bachelor






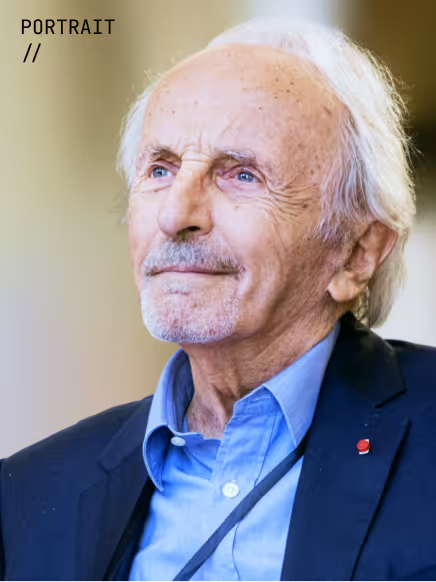
L’intelligence artificielle rend l’information financière plus accessible et accompagne un nombre croissant de décisions d’investissement. Mais comment s’assurer de la fiabilité de ses recommandations ? Dans son édition du 23 octobre 2026, le quotidien allemand Die Welt explore ces enjeux avec l’éclairage de Marie Brière, directrice générale de l’Institut Louis Bachelier et responsable de la recherche investisseurs à l’Amundi Institute.
Comparer des fonds, analyser des rapports financiers ou proposer un portefeuille adapté au profil d’un investisseur : les outils d’IA ouvrent de nouvelles possibilités. Leur utilisation soulève toutefois des questions essentielles sur la qualité des conseils, la responsabilité en cas d’erreur et les conséquences pour les marchés.
Dans cet article signé Frank Stocker, Marie Brière souligne que les grands modèles de langage peuvent formuler des recommandations biaisées, en favorisant certains secteurs ou certaines catégories de titres, ou en extrapolant à tort des tendances passées.
Les risques ne se limitent pas à la pertinence d’un conseil. Marie Brière attire également l’attention sur la vulnérabilité à la manipulation des systèmes utilisés dans l’analyse financière, le conseil automatisé et le trading algorithmique. Elle évoque notamment des simulations en laboratoire montrant que les interactions entre modèles d’IA peuvent faire émerger des comportements de collusion tacite.
La propagation des erreurs constitue un autre point de vigilance : des imprécisions peuvent s’accumuler, se diffuser et influencer les décisions humaines, jusqu’à modifier la dynamique des marchés.
À mesure que l’IA prend une place plus importante dans les pratiques financières, comprendre ces mécanismes devient essentiel. Cette intervention dans la presse internationale souligne le rôle de la recherche pour éclairer les usages de l’IA et mieux anticiper leurs conséquences pour les investisseurs et la stabilité financière.
Retrouvez ci-dessous l’intégralité de l’article dans sa version anglaise.
Frank Stocker, « Auch der KI-Anlageberater kann sich mal irren », Die Welt, 23 octobre 2026.
Frank Stocker — Die Welt, 23 October 2026
Investing has never been easier than it is today; digital assistants analyse investments in seconds. But who is liable for wrong decisions? The EU’s securities regulator now intends to take action, not just to protect retail investors. The influence of new systems is changing the dynamics of entire markets
It takes just a few seconds. The AI recommends specific ETFs, weights the portfolio down to the decimal point and even explains why the strategy suits the investor’s age, assets and risk profile. Investing has never been easier. But does that also make it safe? The fact is that the new technology provides better access to information and lowers the barriers for investors.
However, the more artificial intelligence takes on the role of a financial adviser, the less clear it becomes who bears responsibility for any wrong decisions. There is as yet no clear solution to this legal problem. It becomes all the more significant the faster this technology develops. This is because, for some spectacular applications that could soon become part of everyday life, it is as yet completely unclear how they should be classified legally.
Although algorithms and AI applications have long been used in the financial markets, they have so far been used primarily by professionals. However, the technology is now finding its way into the investment activities of retail investors. ChatGPT, Claude and Gemini analyse annual reports, compare ETFs, calculate portfolio allocations and answer questions that previously required a adviser or analyst. According to a study by researchers at the Universities of Washington and Miami, by the end of 2024 almost half of the retail investors surveyed in the US were already using AI, predominantly to analyse and interpret financial information.
As is always the case with technological developments, Germans are far more sceptical in this regard. A survey commissioned by the credit card provider Visa this summer revealed that 68 per cent of respondents would rather not, or definitely not, have their insurance policies and financial products managed by AI. As many as 86 per cent were critical of investing with the help of AI. Yet even the Germans will soon follow suit. Clear evidence that AI can be helpful in investing can be found, for example, in a study by financial economists Omri Even-Tov, Ben Lourie, Komberlyn Munevar and Alexander Nekrasov. When ChatGPT was briefly banned in Italy in the spring of 2023, the researchers investigated the effects.
Broker data showed that, during that period, Italian retail investors traded in fewer securities, opened new positions less frequently and concentrated their investments more heavily on familiar assets. “Overall, the evidence suggests that generative AI (GenAI) enables broader trading activity for retail investors by reducing the costs of information processing.”
It is therefore only a matter of time before AI becomes widely adopted in personal investing. But who is liable if the AI makes mistakes? After all, it is not without reason that OpenAI’s AI statements conclude with: “ChatGPT may make mistakes. Verify important information.” But is that enough for the AI provider to absolve itself of all liability?
The European Securities and Markets Authority (ESMA) clarified as early as May 2024 in a policy statement that the existing rules for financial service providers also apply when they use AI. Among other things, the statement explicitly refers to risks such as algorithmic biases, poor data quality, non-transparent decisions, excessive reliance on AI, and data protection and security issues. Furthermore: “It is important that the decisions of institutions remain the responsibility of their management bodies, regardless of whether these decisions are made by humans or AI-based tools.” The so-called MiFID II rules for the protection of retail investors also apply in the age of AI.
But are these rules sufficient? Legal scholars Riccardo Ghetti, Claudio Novelli, Philipp Hacker and Luciano Floridi have investigated precisely this. Particularly problematic are issues relating to data quality, the suitability assessment of investment recommendations and the traceability of AI decisions: “When comparing these risks with the applicable EU regulations, we came across significant gaps.”
One legal issue has so far received little attention. According to the German Banking Act (KWG), investment advice is deemed to have been provided as soon as a statement takes personal circumstances into account. A statement such as “This ETF tracks the MSCI World” is therefore merely general information. A statement such as “Based on your age, your assets and your risk appetite, this particular ETF is the right fit for you” may already cross the threshold into investment advice requiring authorisation.
This could prove particularly relevant in the case of modern AI assistants. If a user merely asks a chatbot for general information about ETFs, this is unlikely to constitute investment advice. If, on the other hand, they ask for a specific portfolio proposal based on their age, assets, income, investment horizon and risk appetite, the communication comes very close to the very area that regulators regard as a personal recommendation. The technology is thus operating in a grey area for which many of today’s regulations were never originally designed.
Authors of a study by the Amundi Investment Institute anticipate hyper-personalised digital investment aids in the future, which will provide investors with behavioural guidance in real time. Or: affective AI, which, amongst other things, analyses tone of voice and facial expressions during customer interactions to detect stress or hesitation before these lead to unfavourable financial decisions.
The future possibilities seem limitless. But so do the risks, warns Marie Brière, Director General of the Institut Louis Bachelier, a non-profit financial research institute in Paris. “Large language models provide biased recommendations by, for example, favouring certain sectors and types of securities or incorrectly generalising past trends.”
Even more seriously: the use of AI in financial analysis, automated advice or algorithmic trading is susceptible to manipulation, according to Brière. “Laboratory simulations prove that AI models can generate tacit price-fixing through interaction.” Given that some AI systems have spectacularly run amok, this seems all the more plausible.
And finally, inaccuracies could accumulate and a minor misunderstanding could spread throughout the entire system. “This, in turn, may influence human behaviour and alter market dynamics.” AI systems could therefore plunge the entire financial markets into turmoil.
It is entirely unclear who would be liable in such cases. In light of these challenges, ESMA has just announced that it will make AI a Europe-wide supervisory priority for 2027. The authority intends to systematically investigate how financial firms use AI and what risks this poses for investors. Among other things, the focus will be on distorted or misleading AI outputs, as well as the growing dependence on a small number of technology providers. At the same time, the authority warns that so-called ‘hallucinations’ by language models in investment advice and portfolio management can lead to misleading recommendations, unexpected risks or missed opportunities.
It will take at least a year to see whether, and if so what, new rules will result from the initiative. Yet time is of the essence. At present, AI systems primarily provide guidance and suggestions. However, the closer they come to taking on the role of a personal financial adviser, the more important the question of liability becomes. Technology is developing rapidly. Liability law, by contrast, is evolving much more slowly.